

Most businesses that start as hobbies do not cross the line on a single day. The change creeps: a friend pays for something you made, then a stranger does, then orders become regular, a market stall or an online shop follows, and one day the money is no longer pocket money. The question of when a hobby counts as a business matters because the answer changes what you must do: how you report the income, whether you can deduct your costs, whether you need to register, and what happens if you keep treating trading income as a pastime after the authorities would call it a business.
In short: what turns a hobby into a business
No single test decides the question, in the United States or anywhere else. Authorities look at the whole picture: whether you run the activity in a businesslike way, whether you intend to make a profit, how much time and money you put in, whether the activity earns profits in some years, and whether you depend on the income. Regular selling to customers, with records, prices set to cover costs and profit, and an effort to improve results, points to a business. Occasional sales of things you made for pleasure, with no records and no real attempt to profit, points to a hobby.
- Businesslike manner: separate money, records, licences and a plan point to a business.
- Profit intent: prices, marketing and changes made to improve profit show the activity is run to earn.
- Regularity and time: frequent selling and significant hours look like trading, not a pastime.
- Results: profits in some years, especially a profit in three of the last five years in the US, support business status.
- Dependence: relying on the income for living costs is a strong business signal.
A note on scope: this article is general information, not tax advice. It uses the United States guidance as its anchor because that guidance is published in the most detail, and it frames the principles for readers elsewhere. Your own position depends on your facts and your country’s rules, so check with a qualified tax adviser before you rely on any of it.
What counts as a business in the first place?
Strip away the legal language and a business is an activity carried on with the intention of making a profit by providing goods or services to others, on a continuing basis. Three elements do most of the work in that definition. There is an activity: something you actually do, make, sell or provide, rather than a one-off disposal of your own possessions. There is continuity: the activity repeats, or is set up to repeat, rather than happening once. And there is profit intent: you mean the activity to earn more than it costs, even if it has not managed to yet. Selling your own used bicycle once is not a business. Buying, repairing and reselling bicycles every month, intending to profit, is one, long before it has a name, a logo or premises.
People also ask how to define their business, which is a different, practical question: what do you sell, to whom, and how do you deliver it? That definition matters for pricing, insurance and marketing, and our guide to how to start a business works through it step by step. But notice that the authorities are not asking for your marketing definition. They are asking the factual question above: is this activity, as it is actually carried on, a business? The rest of this article is about the evidence they use to answer it, drawn mainly from the guidance published by the Internal Revenue Service (IRS), the US tax authority, because it sets its reasoning out in unusual detail.
The factors the IRS looks at
The IRS guidance on telling a hobby from a business lists factors to weigh together, and states that no one factor alone is decisive. The same broad factors appear in the guidance of many other tax authorities, because they are really questions about how the activity behaves. They group naturally into three sets: how you run it, why you run it, and what the results look like.
How you run it: businesslike manner, time and expertise
The first factor is whether you carry on the activity in a businesslike manner and keep complete and accurate books and records. A separate bank account, recorded sales and costs, invoices, a pricing method and any required licences all point one way; cash in a drawer and no records point the other. The second is the time and effort you put in: substantial, regular hours suggest an intention to make the activity profitable, although hiring competent help counts too, so a business does not stop being a business because the owner delegates. The third is knowledge: whether you or your advisers have the expertise to run the activity as a successful business, shown by study, experience or taking advice. None of these requires sophistication. A market trader with a notebook, a separate account and prices worked out on paper is running businesslike; a talented maker with none of those may still be treated as a hobbyist until the behaviour changes.
Why you run it: profit intent, dependence and pleasure
Profit intent sits at the centre, and the IRS reads it from behaviour rather than from what you say. Changing your methods to improve profitability, dropping products that lose money, marketing the activity and pricing to cover costs are evidence of intent; repeating the same loss-making pattern for years without changing anything undermines it. Whether you depend on the income for your livelihood is another factor: the more the activity pays your living costs, the more it looks like a business. Personal enjoyment cuts the other way but is not decisive on its own, many people love the work their business does. The question is whether pleasure is the main point, with sales as a by-product, or whether the activity is run to earn, with pleasure as a welcome extra. Your financial position is also considered: someone with substantial other income who funds a loss-making activity year after year looks more like a hobbyist than someone whose savings are genuinely at risk in the venture.
What the results look like: profits, losses and appreciation
Finally, the results. An activity that makes a profit in some years, and the size of those profits relative to the money invested, supports business status. Losses are examined rather than simply counted against you: losses caused by events beyond your control, or normal for the startup phase of that kind of business, are treated differently from losses that continue unexplained for years. A history of turning similar activities profitable in the past also counts in your favour. The last factor is whether you can reasonably expect to make a future profit from the appreciation of assets used in the activity, such as land or breeding stock, which is why some activities with thin yearly trading results can still be businesses.
The three-of-five-years presumption in the US
Alongside the factors, US rules contain a presumption that gives growing activities some certainty. As the IRS guide to whether a hobby is a for-profit endeavour explains, an activity is presumed to be carried on for profit if it makes a profit in at least three of the last five tax years, including the current year. For activities consisting mainly of breeding, showing, training or racing horses, the test is a profit in at least two of the last seven years. Treat the presumption correctly: passing it supports your position strongly, but failing it does not automatically make the activity a hobby. A young business can lose money in its early years and still be a business on the factors, especially where startup losses are normal for the activity and the operation is visibly being adjusted to reach profit. Equally, one profitable year in five, with no records and no changes ever made, is weak evidence however it is described.
Practical signs that you have already crossed the line
Set the formal tests aside and look at your own activity. You are very likely running a business, whatever you call it, if most of the following are true. You sell regularly, weekly or monthly rather than once or twice a year. You have repeat customers or a standing channel, such as a shop listing, a stall or an order book. You buy materials or stock mainly to resell or to make things for sale, rather than for your own use. You set prices by working out costs and adding a margin, and you advertise or post your work where buyers will see it. You keep at least basic records, hold a separate account or wallet for the money, and the income has become a line you rely on in your household budget. And when something loses money, you change it. If that description fits, the remaining question is not whether it is a business, but whether you have done the things a business must do.
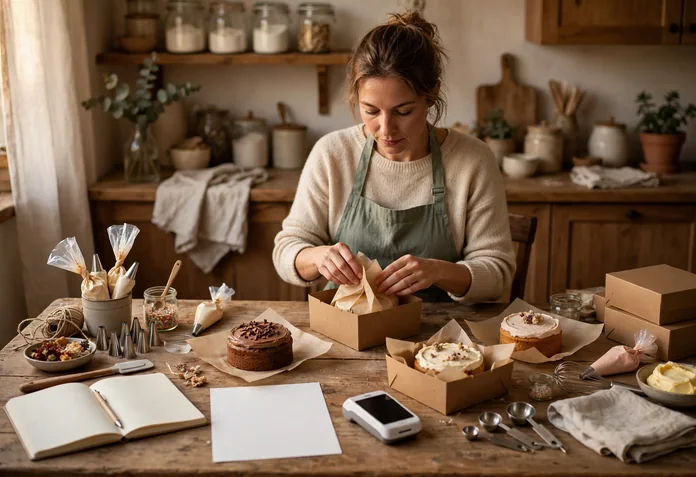
An example makes the boundary concrete. A home baker who sells a cake to a colleague twice a year, at a price that roughly covers ingredients, is enjoying a hobby that occasionally pays. The same baker taking orders every weekend, pricing cakes from a costing sheet, holding a food hygiene certificate, advertising locally and banking the takings separately is running a business, even if it operates from a home kitchen, even if it has no name, and even if the baker still loves baking. The activity did not change; the manner, regularity and intent did. Our guide to how to make a business profitable takes the next step from there: the pricing, cost and cash habits that turn a newly recognised business into one that actually keeps its profit.
What changes when a hobby becomes a business
Tax reporting. Business income must be reported as trading income, and in return the costs of earning it generally become deductible in a way hobby costs are not. In the US, a sole proprietor typically reports on Schedule C, and the IRS guidance on business income and expenses sets out how the hobby and business distinction affects what can be claimed. Hobby income, by contrast, must still be reported, but hobby expenses have far weaker standing. The practical lesson is that crossing the line is not all burden; proper business status is what makes your genuine costs count.
Registration and structure. Depending on where you trade, a business may need to register with a tax authority, a local authority or a companies register, charge sales tax or VAT once turnover passes a threshold, and hold licences for its activity. It is also the moment to choose a structure deliberately rather than drifting as an individual by default: our comparison of LLC, corporation or sole proprietorship explains what each form means for liability, tax and administration. Compliance routines follow from that: filing dates, record retention and renewals become fixed duties, and our small business compliance calendar shows how to spread them across the year so none of them arrives as a surprise.
Money and protection. Separate the business money from household money completely, keep records from the first sale rather than reconstructing them later, and review insurance: a home policy commonly excludes or limits business activity, stock and equipment, and it will not cover a claim by a customer who was hurt by your product or at your premises. None of these steps is expensive at hobby scale. All of them become more painful when they are done late, under pressure, after a letter from a tax authority or a claim.
Premises and people. Two growth steps change the position again, and both are easier from a properly set up base. Renting a stall, a unit or a shop usually requires evidence of trading, records and insurance that an informal hobby cannot produce. Paying helpers, even casually, raises its own questions about employment status, payroll and safety duties, which sit on top of the tax question rather than replacing it. Neither step should be improvised at the last minute; if either is on your horizon within the year, that is itself a sign the activity should be set up as a business now, so the evidence and the paperwork exist when you need them.
The risks of trading while calling it a hobby
The commonest reason people resist the label is the hope that hobby status keeps things simple and tax-free. It does not. Income from a hobby is still taxable income in the US and in most other systems; the label mainly removes your ability to deduct costs and losses properly, it does not remove the duty to declare what you earned. Trading platforms, payment processors and marketplaces increasingly report seller activity to tax authorities, so the gap between what a seller declares and what the authority can see has narrowed considerably. Add the non-tax risks: trading without a required licence or food registration, selling without insurance, and having no clear position if a customer dispute reaches a chargeback or a court. There is also a commercial cost. A business that cannot invoice properly, cannot show records and cannot prove its income struggles to rent premises, win larger customers or borrow, however good its products are.
None of this is a reason to fear crossing the line. It is a reason to cross it deliberately, on a date you choose, with the registrations, records and insurance done in one pass. Founders who make that decision early usually describe it as a relief: the activity is easier to price, easier to grow and easier to defend once it is honestly set up as what it already is.
Common situations, judged on the factors
The marketplace craft seller. A seller who lists handmade items every week, buys materials in bulk for resale stock, photographs and promotes the listings, tracks fees and postage, and adjusts prices when margins are thin is running a business on every factor that matters, even if total sales are modest and the work happens at a kitchen table. Scale is not one of the factors; behaviour is.
The weekend tutor or coach. Occasional unpaid help for friends is not an activity at all in this sense. Paid sessions booked regularly, advertised locally, delivered to a plan with fees set in advance and income the tutor relies on for rent or bills, are a business. The grey zone in between, a few paid sessions a month with no records, is exactly where setting up properly is cheapest: a diary of sessions, a separate account and declared income cost little, and they convert a doubtful position into a defensible one.
The buyer and reseller. Selling your own possessions as you clear them out is disposing of property, not trading. Buying items with the intention of reselling them at a profit, repeatedly, is trading from the first purchase made for that purpose, because profit-seeking motive and frequency are present before the first sale completes. Resellers are often the last to recognise their status, because each individual transaction feels small, while the pattern across a year is unmistakably a business.
The content creator. Videos, streams or posts made for pleasure, which later attract advertising or sponsorship income, sit on the same boundary. Once income arrives regularly, the creator is being paid commercially, is usually putting in scheduled hours, and is often buying equipment for the activity. That equipment buying cuts both ways in the analysis: it is evidence of a businesslike operation, and its cost is the kind of expense that proper business status allows you to claim. Creators who keep treating the income as a windfall from a hobby are the group most often surprised by a tax bill.
Outside the United States
The details differ, the direction does not. Most tax systems ask some version of the same questions: is there a trade, is it carried on commercially, and is profit being sought? The UK, for example, works with its own long-standing set of indicators commonly called the badges of trade, covering profit-seeking motive, frequency of transactions, how the item was acquired and how the sale was financed and organised. Thresholds, registration duties and reporting forms are local, and some countries set a small trading allowance below which occasional income is simplified or ignored for tax. Because those allowances and thresholds change and are easy to misread, treat every figure you see quoted online as a prompt to check your own authority’s current guidance, not as a rule you can rely on.
Keep the boundary under review as the activity changes. Status is judged on the facts of each period, so an activity can move from hobby to business as it grows, and the honest course is to reassess whenever something material changes: a first employee, a premises lease, a jump in turnover, or the point where the income starts paying real household bills. A short note to yourself each year, recording what changed and what you did about it, is cheap evidence that you took the question seriously.
Sources and the advice note
The factor analysis and the three-of-five-years presumption are from the Internal Revenue Service: its guidance on how to tell the difference between a hobby and a business for tax purposes, its guide Is Your Hobby a For-Profit Endeavor?, and its small business income and expenses guidance. This article is general information, not tax advice, and it is not a substitute for advice about your own activity. Tax rules on hobbies and small trading income change, and the outcome in any real case depends on the full facts, so confirm your position with your tax authority’s current guidance or a qualified adviser.
Frequently asked questions
How much do I need to earn before my hobby counts as a business?
There is no single earnings threshold in the IRS test. The authority looks at the whole picture: whether you run the activity in a businesslike manner with complete records, the time and effort you put in, whether you depend on the income, whether you change methods to improve profitability, and whether the activity makes a profit in some years. Regular selling run to make a profit points to a business at almost any scale, while occasional sales from an activity run for pleasure point to a hobby.
What is the three-of-five-years rule for hobby income?
In the United States, an activity is presumed to be carried on for profit if it makes a profit in at least three of the last five tax years, including the current year. For activities mainly involving breeding, showing, training or racing horses, the test is a profit in at least two of the last seven years. Failing the presumption does not automatically make an activity a hobby; the other factors, such as records, effort and changes made to improve profit, are still weighed.
Do I have to pay tax on money from a hobby?
Yes, in the United States and in most other tax systems, hobby income is still taxable income and must be reported. The hobby label does not make the money tax-free. Its main effect is restrictive: hobby expenses and losses have far weaker standing than business costs, so a hobbyist can end up taxed on money that a properly set up business would have offset with genuine costs. This article is general information, not tax advice, so confirm your own position with your tax authority or an adviser.
What should I do once my hobby has become a business?
Keep records of sales and costs, use a separate account for the money, and set prices that are meant to cover costs and leave a profit. Register and obtain any licences your activity and area require, check the insurance position, because a home policy may not cover business activity or customer claims, and sort out how the income will be reported before the next filing date. Doing these steps in one pass, on a date you choose, is far easier than doing them after an authority asks questions.
If my side project becomes a business, is it a business forever?
Only if you continue to run it as one. The tests look at behaviour and results, not at your intentions for the future, so an activity that stops trading, stops being run in a businesslike way and returns to occasional sales for pleasure can be a hobby again. Keep records of when and how the activity changed, because the boundary years are the ones most likely to be questioned, and take advice if significant income or losses are involved.
Does selling online change whether it is a hobby or a business?
The same factors apply in the United States: what matters is how the activity is carried on, not the platform you sell through. Regular listings, repeat buyers, stock bought to resell, prices set from costs and records of sales and fees all point to a business. Marketplaces and payment processors also report seller activity to tax authorities, so online selling is more visible than many sellers assume. Occasional sales of your own used belongings are different; that is disposing of possessions, not trading.
