

Originally published: January 25, 2022. Last updated: Oct 15, 2026.
When stock markets fall, investors reach for gold. The logic is familiar: gold is tangible, scarce, and nobody’s liability, so it should hold value when paper assets wobble. Sometimes it does. But gold is not the simple shield it is often sold as: it has its own crashes, it pays no income, and buying after a record run carries timing risk. This guide gives an honest, data-grounded answer with 2025-2026 context. It is educational, not investment advice.
For gold’s place in a broader retirement plan, see retirement planning for business owners, which positions gold as one diversifier among several.
How Gold Behaves When Markets Crash
Gold’s hedge reputation comes from real episodes: it has repeatedly risen during equity selloffs, currency crises, and geopolitical shocks, when investors flee to assets perceived as safe. Central banks are structural buyers: the World Gold Council reported central-bank purchases of 1,237 tonnes in 2025, a major pillar of demand. But the hedge is imperfect. Gold fell alongside equities in the sharpest liquidity panics, when investors sold everything to raise cash. And over long horizons, equities have compounded far faster: gold preserves purchasing power across decades; it does not build wealth the way productive assets do.
The 2025-2026 Price Context
Gold’s recent run is extraordinary and relevant to timing. It averaged about $3,432 an ounce in 2025, gained roughly 65% that year, and touched a record near $5,595 in late January 2026, per Kitco market data. Record prices reflect genuine demand, but they also mean new buyers are purchasing at levels never seen before. Assets bought at records can still rise, yet the margin of safety is thinner than it was. Anyone adding gold now should size the position for that reality, not for the last twelve months’ chart.
What Gold Costs to Own
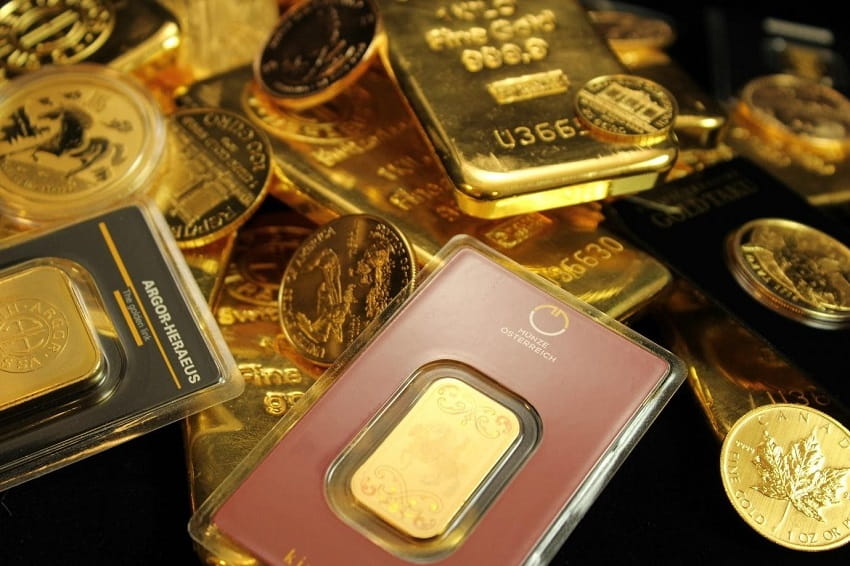
Physical gold carries dealer premiums over the spot price, plus storage and insurance costs, and selling means finding a buyer at a fair bid. Gold ETFs remove storage hassle and trade like stocks, but charge annual expense ratios and you own paper, not metal. Mining stocks offer leverage to the gold price but behave like equities in a crash, which defeats the hedge purpose. Whichever route you choose, understand the all-in cost before comparing gold’s returns to anything else.
The Honest Limits of the Hedge
First, gold pays no dividend and no interest: every year you hold it, you forgo the income productive assets would have paid. Second, it is volatile in its own right, with drawdowns of 30% or more in its history. Third, it does not protect against every risk: inflation-linked bonds, cash reserves, and simply holding less equity each hedge different risks better in different scenarios. Fourth, short-term price moves are driven by sentiment, rates, and currency moves as much as by fear. Gold is a diversifier with a specific job, not a portfolio in a bar.
How Much Gold Makes Sense
There is no universal answer, but most frameworks discuss a modest allocation, often in the single digits to low teens as a share of the portfolio, rebalanced periodically back to target. Rebalancing matters: after a run like 2025’s, an unmanaged gold position grows into an oversized bet. Set the target, rebalance on schedule, and treat gold as insurance you hope underperforms in good years. That is what insurance is for.
Frequently Asked Questions
Does gold go up when the stock market crashes?
Often, but not always. Gold has risen during many equity selloffs and crises, which built its safe-haven reputation. In the sharpest liquidity panics, however, investors have sold gold alongside everything else to raise cash. Treat it as an imperfect hedge, not a guarantee.
Is gold a good investment in 2026?
Gold’s fundamentals, central-bank buying and crisis demand, remain intact, but prices are at record levels after a roughly 65% gain in 2025. Record prices mean thinner margin of safety for new buyers. Size any position accordingly and diversify rather than concentrating.
How much of my portfolio should be in gold?
Most frameworks suggest a modest allocation, often single digits to low teens, rebalanced periodically. The right amount depends on your risk tolerance, time horizon, and what risks you are hedging. This is not investment advice: consider a qualified advisor.
What is the cheapest way to own gold?
Gold ETFs typically have the lowest all-in costs: no dealer premiums, no storage or insurance bills, just an annual expense ratio. Physical gold costs more to buy, store, and insure but carries no counterparty risk. Mining stocks are equities first and hedges second.
Does gold protect against inflation?
Over very long periods, gold has roughly preserved purchasing power. Over shorter periods, its inflation-hedging record is mixed: it can fall in real terms for years. Inflation-linked bonds hedge inflation more directly; gold hedges crisis and currency risk better.
What are the risks of investing in gold?
Price volatility with significant historical drawdowns, no income, storage and insurance costs for physical metal, timing risk after record prices, and opportunity cost versus productive assets. Understand all of them before buying.
